Seven linked UK companies expose the limits of isolated registry checks
A joint UK investigation connected seven apparently unrelated companies, showing why KYB checks must corroborate filings and compare patterns across entities.
What happened
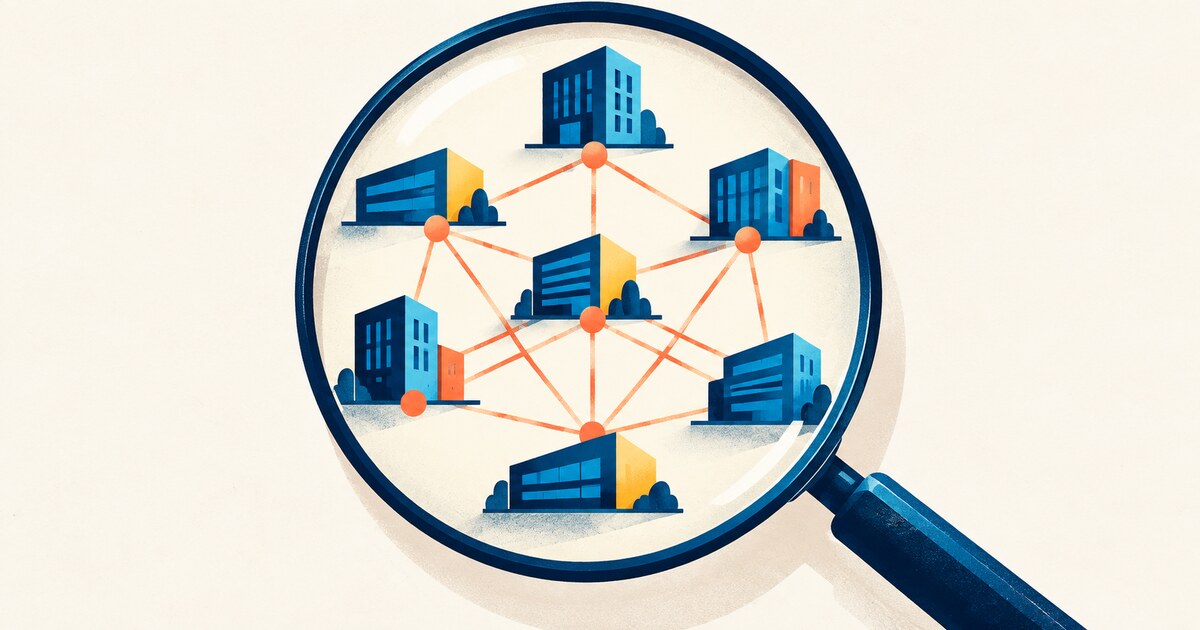
On 24 September 2026, The Insolvency Service and Companies House announced that seven companies had been wound up in the public interest by the High Court in Manchester two days earlier. Although the businesses appeared unrelated on the public register, a joint investigation identified evidence connecting them.
The companies were registered across Lancashire, London, Manchester and Reading and claimed to operate in different areas, including wholesale fruit and vegetables, oil and gas, and property. Investigators found similarities in their incorporation histories, company-name changes and business descriptions.
The investigation also found that accounts filed at Companies House appeared to contain false or misleading auditor information. The audit firms named in those accounts denied conducting the audits. Several companies had no genuine presence at their registered office addresses, and investigators could not confirm legitimate trading activity or identify the actual controllers of some of the businesses. The companies' failure to cooperate prevented those points from being verified.
The official announcement does not say that all seven companies shared one controller. Its narrower finding is still significant: patterns across records, combined with independent checks, revealed links that were not apparent when the companies were viewed separately.
Why it matters for KYB teams
A registry record shows what has been filed; it does not by itself prove that the information is accurate or that the business has a genuine operating presence. In this case, the filings gave the companies an appearance of legitimacy while checks with the named auditors and at registered addresses raised material questions.
Reviewing entities one at a time can also hide weak signals. A name change, generic business description or similar incorporation history may mean little in isolation. When the same patterns recur across several companies, they can become relevant to the risk assessment. KYB workflows therefore need to retain historical records and connect recurring attributes across customers and cases without treating any single match as conclusive.
The case also reinforces the need to corroborate registry information across independent sources. Where ownership, trading activity, registered-office presence or a professional relationship cannot be confirmed, that uncertainty should remain visible and drive further review rather than being converted into a definitive result.
These checks cannot end at onboarding. Changes to company names, addresses, auditors, filing behaviour, insolvency status or enforcement exposure can alter the reliability of an earlier decision. Continuous monitoring should reopen the assessment when new information weakens the evidence on which the original conclusion depended.
What teams should review
- Are previous company names and incorporation changes retained alongside the current registry profile?
- Is the registered office and claimed trading presence corroborated when those details are material to the risk assessment?
- Are auditor or accountant relationships independently checked before they are treated as evidence of legitimacy?
- Can the workflow identify recurring addresses, filing patterns, business descriptions or professional relationships across apparently unrelated entities?
- Are inconsistencies between registry filings, declared activity and external evidence preserved and escalated?
- If legitimate trading, ownership or control cannot be established, can the case remain unresolved and trigger enhanced due diligence?
- Do material changes to names, addresses, auditors, filings, insolvency status or enforcement exposure trigger re-review?
- Can reviewers reconstruct why several signals were treated as a meaningful connection without presenting one shared attribute as proof?