Two paper companies reveal hidden-control signals in a Rs3.2bn trade network
Two paper companies, overlapping digital access and implausible trade capacity show how hidden control can emerge only when KYB signals are connected.

What happened
Business Recorder reported that the Collectorate of Customs Airport Karachi had identified imports worth Rs3.2 billion routed through two allegedly fake companies operating as “market IDs” for undisclosed operators. The Collectorate recommended forming a joint investigation team to examine possible trade-based money laundering and concealed ownership.
The case began with 10 goods declarations covering 71,815 internet routers imported without the required Pakistan Telecommunication Authority certificate. After the consignments were confiscated, several people reportedly claimed ownership of separate portions of goods recorded within the same declarations. That prompted a wider examination of the companies behind the imports.
According to the investigation report cited by Business Recorder, both entities were paper companies registered in the names of front men. One declared address was a rice and flour shop; the other was a rented family home. One company was registered with the Federal Board of Revenue as a service provider and general order supplier rather than as an importer.
The digital trail connected the two companies more directly. Their WeBOC customs user IDs had been accessed from 2,983 and 2,732 unique IP addresses respectively, with 1,048 addresses shared between them. Investigators said the pattern indicated that multiple hidden operators may have been using the same company identities and customs credentials.
The companies’ apparent financial capacity also did not match the scale of their activity. Their owners initially declared combined capital of Rs2.2 million, later reaching approximately Rs77.7 million, while total imports were valued at about Rs3.2 billion. Customs also increased the assessed value of the imported goods by Rs1.3 billion. These remain reported findings from an investigation rather than a final criminal determination.
Why it matters for KYB teams
The case shows why confirming that a company exists is not the same as establishing who actually controls or uses it. A registry entry, tax number and customs account can all appear valid while the operating reality sits with undisclosed parties behind the registered entity.
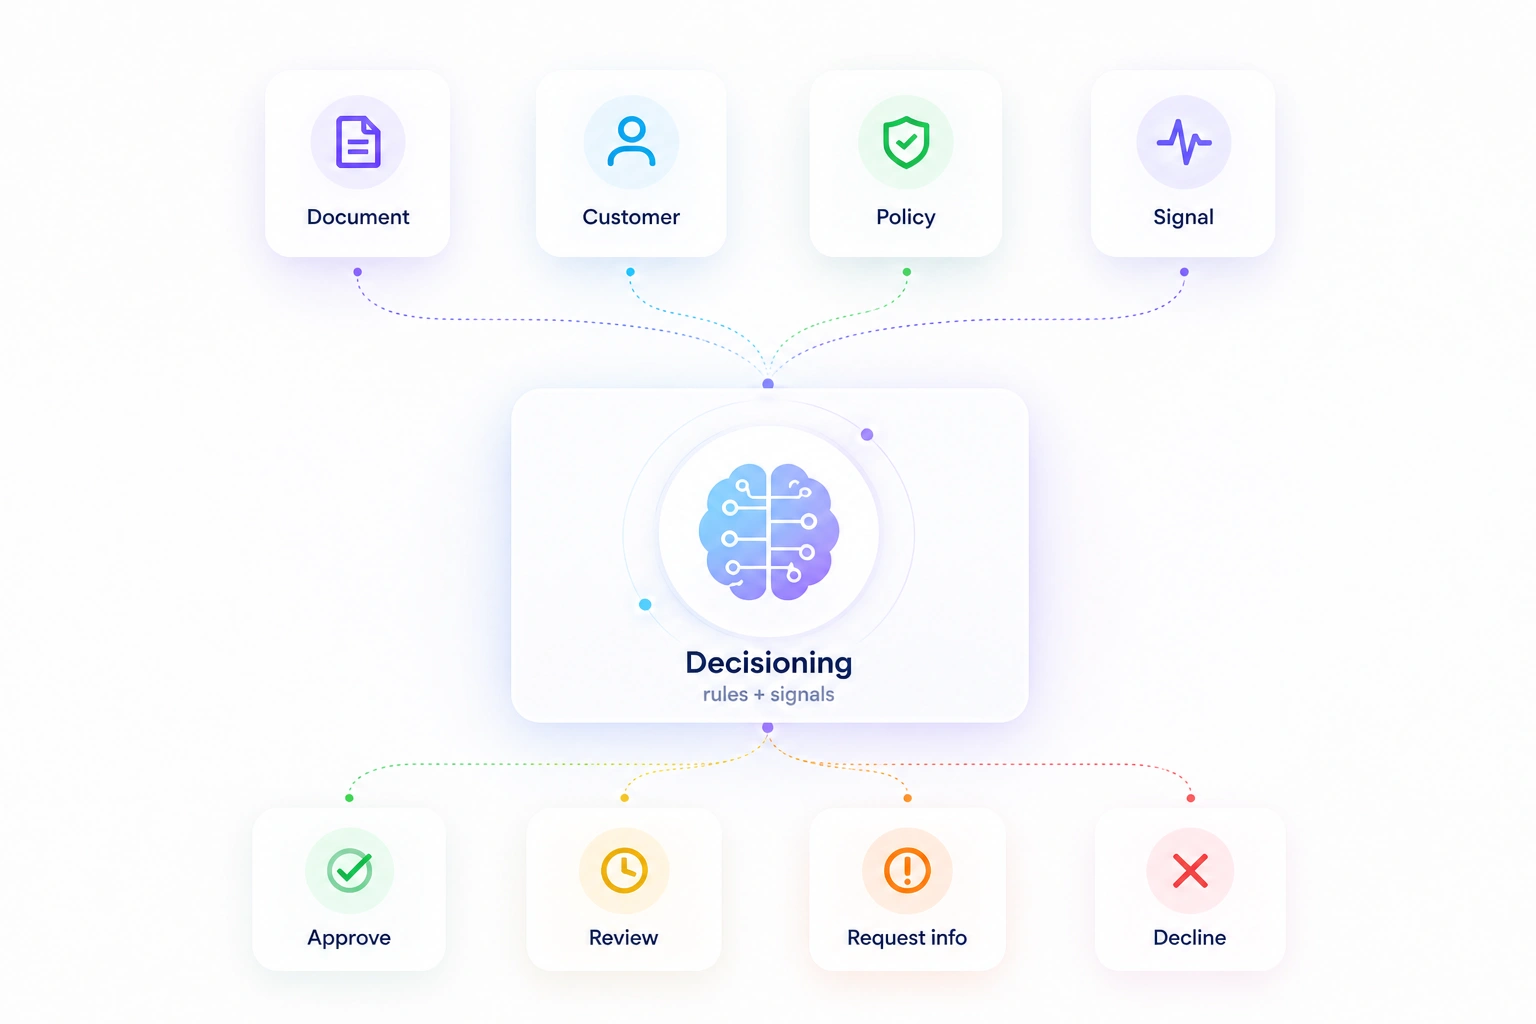
No single signal proves hidden control. A residential address, shared IP address or low declared capital may each have an innocent explanation. The risk becomes materially stronger when the signals converge: implausible premises, activity outside the registered business profile, overlapping access infrastructure, fragmented ownership claims and trade volumes that do not fit the company’s apparent resources.
That makes cross-source comparison central to KYB. Registry information needs to be tested against tax status, trading permissions, physical presence, declared business activity, shipment data, counterparties and digital-access evidence. Broader data coverage is valuable only when those records can be resolved to the same entity and their inconsistencies remain visible.
The 1,048 shared IP addresses are especially relevant as a network signal. Shared infrastructure is not automatically suspicious, but extensive overlap between supposedly separate businesses should trigger analysis of common users, devices, credentials, contact details, intermediaries and beneficial owners. The purpose is to determine whether the apparent separation between the companies reflects economic reality.
The pattern also emerged through repeated trade activity rather than a single onboarding event. Effective continuous monitoring should therefore compare later behaviour with the company’s original profile and reopen the ownership assessment when scale, counterparties or access patterns no longer make sense.
What teams should review
Teams assessing companies involved in trade or cross-border payments should review the following controls:
- Is the registered address consistent with a functioning business of the stated type and scale?
- Does the company’s registered activity, tax status and licensing support the transactions it is conducting?
- Are declared capital, revenue and operating resources plausible relative to its trade or payment volumes?
- Can the workflow identify shared IP addresses, devices, credentials, contact details or intermediaries across separate companies?
- Are related declarations, shipments, payments and counterparties aggregated before thresholds and patterns are assessed?
- Do nominee directors or owners trigger additional work to establish the people exercising actual control?
- Are inactive, suspended, blacklisted or commercially inconsistent counterparties routed for investigation?
- Can reviewers preserve the source, date and rationale behind each network link without treating the signal itself as proof?